The garment industry is the most crowded in all of manufacturing. Tens of thousands of factories across Asia compete for the same orders, and while the garment industry in the region is thriving, it is a hard business to stand out in. This report gives an overview of the garment industry as it stands in 2026, what to expect when producing clothing in Asia and particularly China, and the problems you will meet if you set up production without help.
Garment Industry Overview & Key Statistics
a. Textile and apparel industry description
China is the largest producer and exporter of textiles and clothing in the world, but its lead is narrowing. China’s share of world clothing exports was 29.6% in 2024, the lowest since 2010 and falling each year, as production of basic garments moves to lower-cost countries. The EU is second at around 8% of world exports, followed by Vietnam at about 5%, with about US$46 billion of textile and garment exports in 2025 (estimate, of which garments about US$36.6 billion), Bangladesh at US$38.70 billion of ready-made garment exports in FY2025-26 (EPB), and India at around US$37 billion. Global trade in textiles and apparel reached roughly US$900 billion in 2025, and the global apparel retail market about US$1.9 trillion.
China’s garment industry remains unrivalled in scale, but the story since 2020 is one of the garment industry redistributing: China keeps the technical, high-value, and fabric-intensive work, and the simple, labor-intensive work goes to Vietnam, Bangladesh, Cambodia, and India, often in factories that Chinese companies own.
b. Global garment production: China vs. other regions of the world
China’s advantages in the garment industry are not primarily about wages any more; they are about fabric, capability, and speed. China produces the majority of the world’s textile fiber and fabric, so a garment made in China is made from fabric a few hours away, while a garment made in Vietnam or Bangladesh is usually made from fabric imported from China.
That gives Chinese factories shorter lead times, more fabric choice, and the ability to make complex garments, technical sportswear, outerwear, and tailored pieces, that lower-cost countries struggle with. Rising labor costs and competition from the region have pushed the simplest work out, but China’s decades of experience, modern infrastructure, and supply-chain integration keep it the leading sourcing country for anything beyond basic garments.
c. What garments are commonly produced in China
- T-shirts, polos, and knitwear
- Jackets, coats, and technical outerwear
- Sportswear and activewear
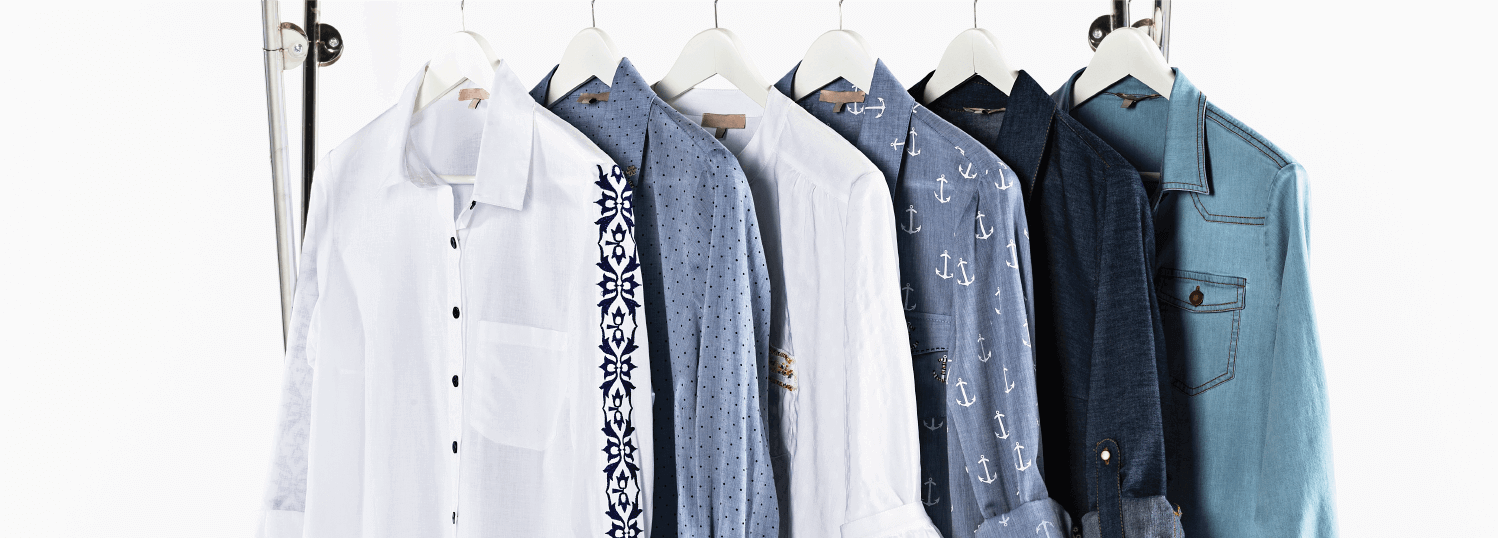
- Jeans and denim
- Underwear, swimwear, and shapewear
- Kids’ wear and infant clothing
- Uniforms and workwear
d. Year-on-year apparel industry growth
China’s garment exports fell 5.0% in 2025 to US$151.18 billion, and textile and garment exports together fell 2.4% to US$293.77 billion (China customs, GACC), as the country shifts from investment-led to consumption-led growth, more production serves the domestic market, and manufacturers move up the value chain into sportswear, outerwear, and technical garments that need more skilled labor and more investment.
China’s domestic apparel market is now among the largest in the world and absorbs a growing share of what its garment industry produces. Export volumes in basic categories will keep declining; export value in technical categories is holding.
Why China is the Right Choice for Garment Production
a. Garment production capacity
China’s garment industry capacity is unmatched. The country produces the largest share of the world’s textile fiber and fabric, and its apparel output runs to tens of billions of pieces a year. More important than the volume is the structure: clusters of specialized suppliers, knitwear in Zhejiang, denim in Guangdong, down jackets in Jiangsu, sportswear in Fujian, where every input, fabric, trims, labels, packaging, is within reach and the factories have made the product before.
Chinese garment factories are also automating faster than competitors, with computer-controlled cutting, automated sewing for simple seams, and digital printing raising productivity and offsetting higher wages. The largest domestic groups, Shenzhou International, Heilan, Semir, Bosideng, and Youngor, are among the largest garment manufacturers in the world.
b. Textile worker skill level
Compared with other low-cost countries, China’s garment industry has a large, skilled workforce and, above all, skilled management. Sewing is low-skilled work everywhere; the difference is the pattern makers, production managers, and quality staff who run a factory efficiently and keep lead times short. That layer is deep in China and thin almost everywhere else.
c. Technological advantages in the apparel industry
With skilled labor and modern equipment, Chinese factories produce lower volumes of higher-value, more technical garments than the region’s alternatives: performance sportswear, seamless knits, waterproof and breathable outerwear, and garments built with bonded seams, laser cutting, and engineered fabrics. These are the products that need a factory with the right machines and the experience to use them, and they are where China’s garment industry has moved as basic work has left.
d. Well-developed supply chain and transportation system
China’s supply chain and its investment in ports, roads, and rail give its garment industry a base competitors cannot match. Its customs clearance, trade infrastructure, logistics services, and shipment reliability outrank every other country in the region, and its high-speed rail and road networks put most garment clusters within a few hours of Shanghai, Guangzhou, or Shenzhen, which makes factory inspection, due diligence, and quality control practical to carry out in person.
e. Challenges in China’s garment industry
The key challenge in China’s garment industry is labor cost. The younger generation of workers is better educated and expects better pay, and the workforce is shrinking as the generation that built China’s growth retires. A Chinese garment worker now costs several times a Bangladeshi one and roughly twice a Vietnamese one, and buyers of simple garments have moved accordingly.
Manufacturers have responded by moving inland, where the western and central provinces now hold well over a quarter of China’s textile and apparel production, with government tax incentives to encourage the shift, and by automating.
The lower-cost alternatives carry trade-offs. Wages are low where skills and experience are thinner, infrastructure is less developed, transport costs and lead times are higher, and quality is less consistent, with many factories confined to simple, low-value items. Since 2025 there is a new factor: US tariffs differ by country of origin, which has made assembly location a pricing decision for US-bound clothing (see the tariff box below).
Section 301 forced-labor tariff, effective 24 July 2026: Vietnam 12.5%; Bangladesh, Indonesia, India, Cambodia and Pakistan 10%. Articles covered by Section 232 are excluded, so the tariffs do not stack. Verify current rates before ordering.
Even so, for anything technical, fabric-intensive, or quality-sensitive, China’s garment industry keeps its advantages: modern infrastructure, skilled labor, and efficient processes.
Potential Problems in China’s Garment Industry
a. Time problems in the garment industry
The most common problem for companies sourcing garments from China is inadequate lead-time planning. Sourcing the right fabric takes time and attention, and errors cause delays. Clients without a local presence cannot maintain the control and awareness needed to prevent them, and if a supplier breaches the contract, a client with no presence in China has little practical way to enforce it. Setting up a garment production line is easy; getting from design files to approved samples to bulk production is slow when planning and coordination are inexperienced or decentralised, and building efficient logistics in the region is costly and time-consuming.
b. Quality problems in the garment industry
Quality in the garment industry fails at predictable points: inadequate supplier assessment, weak quality assurance at the sampling stage, fabric substitution between sample and bulk, measurement drift across sizes, and finishing defects that only show after washing. Chinese suppliers under price pressure will use cheaper fabric or trims unless the specification is precise and inspected. Specification, in-line inspection, and pre-shipment inspection against an AQL standard are what prevent a quality failure from reaching the customer.
c. Cost problems in the garment industry
Garment costs are dominated by fabric, then labor, then trims and packaging, and the fabric quote is where most cost errors happen. Buyers who do not understand fabric pricing, or who accept a quote without a fabric specification, end up paying more for less. Minimum order quantities are the second cost problem: below a factory’s MOQ, per-unit prices rise sharply, and a brand that does not know the MOQ landscape either overpays or overorders.
d. Planning problems in the garment industry
A garment program has many moving parts: fabric lead times, sampling rounds, size sets, fit approvals, trims, labels, packaging, and testing, all of which have to converge on a production date. Without a plan that accounts for each, the production date slips. Fabric is the usual culprit, since custom fabric can take longer to produce than the garment itself.
e. Risk problems in the garment industry
The risks of contracting with a Chinese garment factory without local presence are the general ones: no transparency into progress, no practical enforcement, and exposure to a supplier who cannot deliver. Compliance is the specific one: garments sold in the US and EU face restricted-substance rules, labelling requirements, and, for children’s wear, mandatory safety testing, and a factory that does not hold the relevant certifications will produce goods you cannot legally sell.
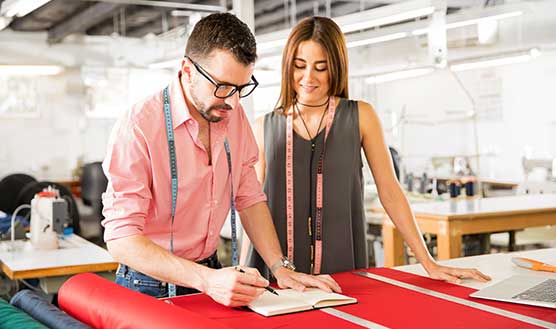
Quality control on the line is what separates a garment that sells from one that comes back.
Our Recommendations for Textile and Apparel Production
a. For reducing time required in the garment industry
Intrepid Sourcing plans the program from fabric lead time backward, with sampling rounds, size sets, and testing scheduled so that the production date holds. We work with garment factories in China, Vietnam, Indonesia and Bangladesh that have the capacity and the category experience your product needs, and we manage the process on the ground so that delays are caught when they can still be fixed.
b. For ensuring quality in the garment industry
We write the specification, fabric, construction, measurements, trims, and tolerances, in a tech pack the factory quotes and produces against, and we inspect against it: fabric checks, in-line inspection, and pre-shipment inspection to an agreed AQL. Our quality assurance covers the tests your market requires, from fiber content and colorfastness to restricted substances and CPSIA for children’s wear.
c. For reducing cost in the garment industry
We quote with fabric, labor, trims, and packaging broken out, so you can see where the cost sits and judge a supplier’s price against the market. With current knowledge of fabric and factory pricing across China and Vietnam, we help you choose the country and the factory that gives the right cost for your product and your markets, including tariff exposure.
d. For planning in the garment industry
We run the program as a whole, from tech pack through fabric sourcing, sampling, fit approval, production, and shipment, with one point of contact and a schedule you can see. For brands starting out, we help set the range and the order quantities so that MOQs work for you rather than against you.
e. For minimizing risk in the garment industry
We verify factories before placing work, contract under the local law of the manufacturing location with terms that can be enforced, and confirm certifications directly with the issuing bodies. If you are developing a clothing product, the place to start is our clothing manufacturing service, which covers everything in this report from design to delivery. The clothing samples phase starts at $497, and we have offices in Hong Kong and the manufacturing regions.
Last reviewed: October 2026
Sources
- China Customs (GACC), December 2025 export table: http://english.customs.gov.cn/
- Bangladesh Export Promotion Bureau (EPB): https://epb.gov.bd/
- Office of the United States Trade Representative (Section 301): https://ustr.gov/