
China monetary policy has been debated for two decades, and the debate usually comes down to the currency. The yuan, officially the renminbi or “the people’s currency”, has been accused of being deliberately undervalued to promote exports, defended as a legitimately managed rate, and, since 2015, watched as it has moved in both directions.
Earlier currencies in China used the name yuan from the late nineteenth century, often tied to a colonial power. The modern currency was first issued by the Communist government in 1948 and reissued in 1955 at 10,000 to 1 after the hyperinflation of the civil war years. What it is worth today, and how it is managed, is the practical subject of China monetary policy for anyone trading with the country.
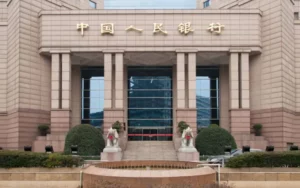
China’s central bank: the People’s Bank of China in Beijing.
China Monetary Policy
China monetary policy is set by the People’s Bank of China, which states its objective as maintaining the stability of the value of the currency and thereby promoting economic growth. The political element is plain, and the PBOC pursues the objective through four main instruments, which differ from those a Western central bank leans on.
- Interest rates. Lowering the benchmark rates encourages firms and households to borrow and spend. Since 2019 the main policy rate has been the Loan Prime Rate, set monthly from a panel of banks and guided by the PBOC’s own lending rate, which replaced the older administered benchmark.
- Reserve requirements. Cutting the ratio of deposits banks must hold releases liquidity into the banking system and lets commercial banks lend more. The PBOC uses reserve ratio cuts more actively than most central banks, and they are often the first signal of a policy easing.
- Open market operations and lending facilities. The PBOC injects or withdraws liquidity through repos and through medium-term lending facilities to banks, and it targets credit to particular sectors through relending programmes, which is a tool most central banks do not use.
- The exchange rate. The PBOC sets a daily reference rate for the yuan against the dollar and allows trading within a band around it, currently 2% either side. The rate is managed against a basket of currencies rather than the dollar alone, and capital controls limit how much money can move in or out, which is what makes managing it possible.
The exchange rate is the distinctive feature of China monetary policy. A country with an open capital account cannot control both its exchange rate and its interest rates; China controls both by restricting capital movement. That gives the PBOC room to cut rates to support domestic growth without the currency collapsing, and it is why China monetary policy can pursue domestic and external objectives at the same time.
The Importance of the Chinese Renminbi
The undervaluation argument against China monetary policy was strongest in the 2000s, when the yuan was effectively pegged and China’s trade surplus was growing fastest. The yuan then appreciated steadily from 2005 to 2014, and the IMF concluded in 2015 that it was no longer undervalued.
In August 2015 the PBOC changed the way the daily reference rate is set, which produced a sharp depreciation and a scare in global markets, and since then the rate has moved in both directions with the dollar cycle, weakening through 2022 to 2024 and appreciating modestly in 2025. The accusation now heard less often is deliberate undervaluation; the more common criticism is opacity about how the reference rate is set.
The renminbi’s international role has grown, from a currency barely used outside China to one that settles a meaningful share of China’s own trade. Over 30% of China’s trade was settled in yuan in 2025, against around 2% a decade earlier, and the IMF added the yuan to its Special Drawing Rights basket in 2015, effective October 2016, alongside the dollar, euro, pound, and yen. It remains a small share of global reserves and of international payments, because capital controls make it inconvenient to hold, and that trade-off, control versus international use, is the central tension in China monetary policy.
The renminbi is managed against a basket, not floated, and capital controls are what make that possible.
What China Monetary Policy Means for a Buyer
For a company buying from China, China monetary policy shows up in three places. The first is the quote: a factory that quotes in US dollars carries the exchange risk and prices it in, while one that quotes in yuan passes it to you, and which is better depends on where you think the rate is going. Quotes are usually valid for a defined period for exactly this reason.
The second is payment. Paying a Chinese supplier in yuan, through a cross-border yuan account, has become far easier as the currency has internationalised, and it can be cheaper than paying in dollars because the supplier does not need to convert. Paying in dollars is still the default and is simpler for most buyers.
The third is tariffs. Because the yuan is managed rather than floated, it does not adjust freely to absorb tariffs imposed on Chinese goods, so the cost of those tariffs lands on the importer rather than being offset by a weaker currency. That is one reason the 2025 tariff rounds passed through to landed costs so directly. Understanding how currency, payment terms, and tariffs interact in a specific product’s cost is part of what our manufacturing analytics and product sourcing services cover.