
The fashion accessories industry offers a durable business idea for anyone in product manufacturing, and the fashion accessories industry supports everything from single-product brands to global houses. This report covers the fashion accessories industry as it stands in 2026, why China remains its production base, and the problems specific to footwear and bags that a brand will meet setting up production without help.
Fashion Accessories Industry Overview & Key Statistics
a. Shoes and bags industry description
Fashion accessories are items that complete an outfit: bags and purses, ties, belts, scarves, caps, hats, and shoes. China is the single largest manufacturer in the fashion accessories industry worldwide. It has been the largest footwear producer for decades and has become a major producer of luggage and bags over the past twenty years.
China produces well over half of the world’s footwear by volume (World Footwear) and exports around US$50 billion of footwear a year, with bags and luggage exports adding roughly US$30 billion. Its share of world footwear exports by value has fallen from over a third a decade ago as production has moved to Vietnam, Indonesia, and India, but it remains the largest single producer by a wide margin and the dominant supplier in most price segments below luxury.
b. Global shoes production: China vs. other regions of the world

The competitive picture in footwear has changed more than in almost any other part of the fashion accessories industry. Vietnam has become the second-largest footwear exporter and the primary production base for the major athletic brands, Nike and Adidas among them, which moved substantial capacity there from 2010 onward and accelerated after 2018. Indonesia, India, and Bangladesh have taken share in volume footwear. Italy, Spain, and Portugal hold the European premium and luxury segment on craft and leather quality.
China’s position now rests on breadth rather than cheapness: it makes every kind of shoe and bag at every price point below luxury, has the deepest material supply, and can handle small runs that Vietnamese volume factories will not accept. For a brand ordering a few thousand pairs, China is usually the only realistic option in Asia.
c. Commonly produced fashion accessories industry goods in China
- Leather and synthetic shoes
- Casual and canvas footwear
- Sports and athletic shoes
- Handbags, totes, and purses
- Backpacks and laptop bags
- Suitcases and travel luggage
- Wallets and small leather goods
- Belts, caps, hats, and scarves
d. Year-on-year footwear industry growth

Footwear and bag exports from China have declined over recent years for three reasons: rising labour costs, which have pushed volume production to cheaper countries; tariffs, which since 2018 have made Chinese-made goods more expensive in the United States specifically; and the growth of Chinese domestic demand, which absorbs a growing share of what the country’s factories make. Chinese exports of footwear, bags, and related consumer goods fell again in 2025 as Western demand softened.
The trends shaping the fashion accessories industry now are sustainability, with recycled materials, chrome-free leather tanning, and traceable supply chains moving from differentiator to requirement; the continued growth of sneakers and casual footwear at the expense of formal shoes; and direct-to-consumer brands taking share from traditional retail across bags and shoes alike.
Why China is the Right Choice for Fashion Accessories Production
a. Fashion accessories production capacity
China’s fashion accessories industry is organised into clusters that contain everything a product needs. Footwear is concentrated in Fujian, particularly around Jinjiang and Quanzhou for athletic shoes, in Guangdong for fashion and leather footwear, and in Zhejiang for volume production. Bags and luggage cluster in Guangdong, especially Baigou and Shiling, which is the largest leather goods and bag production centre in the world. Around each sit the tanneries, synthetic material suppliers, hardware and zip suppliers, sole manufacturers, and last makers.
That density is the advantage. A bag design needing a particular hardware finish, or a shoe needing a specific sole construction, can be developed in weeks because every input is within reach, and a factory can produce a sample, revise it, and produce again faster than anywhere else.
b. Technological advantages in the shoes and bags industry
Chinese factories in this sector have adopted computerised cutting, automated stitching for repetitive operations, direct injection and moulding for soles, 3D design and virtual sampling, and digital printing on synthetic materials. China installed 295,000 industrial robots in 2024, more than half the world’s total (IFR), and while footwear and bag making remain relatively labour-intensive, automation has raised consistency and reduced the cost gap with lower-wage countries.
c. Modern logistics infrastructure
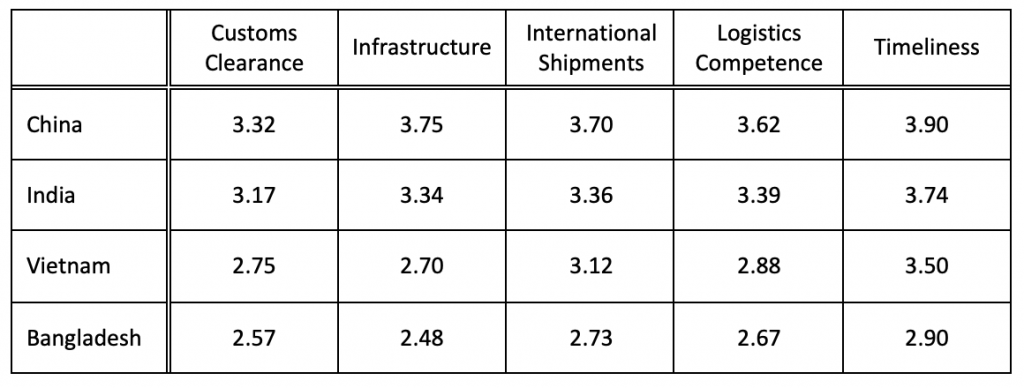
Shoes and bags are bulky relative to their value, which makes packing efficiency and freight cost significant, and both categories are seasonal, which makes delivery reliability critical. The production clusters sit close to Xiamen, Shenzhen, Guangzhou, and Ningbo, among the busiest container ports in the world, with forwarding and consolidation services built for mixed-SKU consumer goods shipments.
Potential Problems in China’s Fashion Accessories Industry
a. Time problems in the fashion accessories industry
Footwear development is slow and iterative. A shoe requires a last, the form the shoe is built around, plus a sole mould, and both are tooling with lead times of their own; several rounds of fitting samples are normal before a shoe is right. Bags are faster but still need pattern development, hardware sourcing, and material approval. Both categories are seasonal, and the Chinese New Year shutdown falls in the middle of most production calendars.
b. Quality problems in the fashion accessories industry
The recurring failures are material substitution, a lower grade of leather or a thinner synthetic than specified; adhesive failure, where soles separate or linings lift after a few months, which is the most common footwear complaint and is invisible at inspection; hardware that corrodes or breaks; and colour and finish variation between production lots. Compliance adds a further layer: chromium VI limits in leather under EU REACH rules, azo dye restrictions, and, for children’s footwear and bags, small parts and phthalate testing. None of these can be judged from a sample by eye; they require laboratory testing and, for adhesion, accelerated wear testing.
c. Cost problems in the fashion accessories industry
Materials dominate the cost of both shoes and bags, and leather, synthetics, and hardware all move in price. Tooling for footwear, lasts and sole moulds, is a substantial upfront cost per style, which is why footwear minimums are higher than most product categories and why a brand should not launch with a wide range of styles. Since 2025, US tariffs on Chinese goods have added a layer that for volume footwear can outweigh China’s other advantages, which is a large part of why athletic production has concentrated in Vietnam.
d. Planning problems in the fashion accessories industry
A footwear range needs a size run for every style and colour, and each size requires a graded last, which multiplies the development work. Add materials, hardware, packaging, and testing, and the coordination burden is larger than the unit price suggests. Sampling has to be scheduled with enough time for two or three rounds, because a first shoe sample is rarely right.
e. Risks in the fashion accessories industry

Design copying is the specific risk of the fashion accessories industry. Bag and shoe designs are easy to replicate, a successful style appears from other suppliers within a season, and design registration in China plus a supplier agreement with exclusivity terms are the practical defences. Counterfeiting is the sharper version of the same problem in this category, since accessories are the most counterfeited product class in the world; registering trademarks in China before approaching suppliers is essential, and the intellectual property article covers why. The general risks of contracting without a local presence apply throughout.
Our Recommendations for the Fashion Accessories Industry
a. For reducing time required
Intrepid Sourcing plans a fashion accessories programme backward from the season, with last and sole tooling, sampling rounds, materials, and testing scheduled around the Chinese New Year shutdown, and places work with factories in the right cluster that have made comparable products.
b. For ensuring quality
We specify materials, leather grade and thickness, synthetic specification, hardware finish, adhesive, and construction in writing, and we test against them, including chromium VI and azo dye testing for leather, adhesion and flex testing for footwear, and children’s product testing where it applies. Our quality assurance service covers in-line and pre-shipment inspection against an approved sample.
c. For reducing costs
We quote fashion accessories industry work with materials, tooling, labour, and packaging broken out, so you can see where cost sits and judge a re-quote when leather or hardware prices move. We advise on range size, because tooling cost per style is the largest avoidable expense for a new footwear brand, and we compare China against Vietnam where tariffs make the difference.
d. For planning
We manage the range as one project: lasts, patterns, size runs, materials, hardware, packaging, and testing coordinated to a single date with one point of contact.
e. For minimizing risk
We verify factories before placing work, register designs and trademarks in China where warranted, and contract under Chinese law with terms covering exclusivity and design ownership. If you are developing bags or footwear, the place to start is our private label package for products built on an existing design, or our product sourcing service for a custom range.